
October 21, 2026
Why Tax Planning Is an Essential Part of Retirement Planning
Introduction
When most people think about retirement planning, they focus on how much they have saved, how their investments are performing, and whether they will have enough income to maintain their lifestyle.
While these are all important considerations, there is another factor that can have a meaningful impact on retirement success: taxes.
After spending decades accumulating retirement savings, the focus eventually shifts from building wealth to using those savings to fund retirement. How and when you withdraw money from your accounts can influence how much of your savings you ultimately get to keep.
This is why tax planning should be an important part of any comprehensive retirement strategy.
1. Not All Retirement Income Is Taxed the Same
One of the most important aspects of retirement tax planning is understanding how different sources of income are taxed.
For example:
- Traditional IRAs/401(k)s: Withdrawals are generally subject to ordinary income taxes, except to the extent they represent after-tax amounts.¹
- Roth IRAs/401(k)s: Qualified distributions are generally tax-free.²
- Taxable investment accounts: Investment gains may qualify for preferential capital gains tax rates, depending on the investment and holding period.¹
- Social Security: Depending on your overall income, a portion of your benefits may be subject to federal income taxes.³
Because these income sources receive different tax treatment, the order and timing of withdrawals can make a difference in your overall tax liability.
Planning note:
Having different types of retirement accounts can provide flexibility when deciding where to generate income each year.
2. Tax Planning Should Begin Before Retirement
Many people wait until they retire to begin thinking about taxes on their retirement income.
However, some of the most valuable planning opportunities may occur during the years leading up to retirement.
This leads into another critical time for planning which is just after retirement. For example, someone who retires at age 62 but does not begin Social Security or required minimum distributions immediately may have several years when their taxable income is lower than it was during their working years.
This period may create opportunities to evaluate strategies such as Roth conversions, realizing capital gains, or adjusting withdrawals from tax-deferred accounts.²
Of course, these strategies are not appropriate for everyone. The potential benefits depend on an individual’s current tax situation, anticipated future income, and long-term financial goals.
Planning note:
The years between retirement and the start of required distributions can present opportunities to evaluate your long-term tax strategy.
3. Small Decisions Today Can Affect Taxes Tomorrow
Retirement tax planning is not simply about minimizing taxes in the current year.
Sometimes, a decision that reduces taxes today can create a larger tax obligation later.
For example, consistently withdrawing from taxable investment accounts while allowing traditional IRA assets to continue growing may preserve tax-deferred savings in the short term. However, it could also result in larger required minimum distributions later in retirement.²
Likewise, a Roth conversion may increase taxable income today but potentially reduce the amount held in tax-deferred accounts and provide tax-free qualified distributions in the future.²
The important consideration is how today’s decisions may affect taxes over the course of retirement.
Planning note:
Paying the least amount of tax this year does not necessarily mean paying the least amount of tax over your lifetime.
4. Taxes Can Affect More Than Your Investment Accounts
Another important consideration is that retirement income can influence expenses beyond your federal income tax bill.
For example, higher income may result in increased Medicare Part B and Part D premiums for certain retirees.⁴
Additionally, withdrawals from retirement accounts, investment gains, and other sources of income may affect how much of your Social Security benefits are taxable.³
This means that a financial decision involving one account can sometimes have consequences elsewhere in your retirement plan.
Understanding these interactions can help retirees make more informed decisions about how and when to generate income.
Planning note:
Retirement income, taxes, Social Security, and Medicare should be evaluated together rather than as separate planning decisions.
5. Tax Planning Is an Ongoing Process
Tax planning is not something that should be completed once and forgotten.
Your financial circumstances can change throughout retirement. Investment performance, changes in spending, new income sources, tax legislation, and family circumstances can all influence your tax situation.
For this reason, reviewing your tax strategy regularly can help identify opportunities that may otherwise be overlooked.
Some of the most important decisions may include:
- Evaluating the timing of retirement account withdrawals
- Considering whether Roth conversions make sense
- Reviewing capital gains and losses in taxable accounts
- Planning for required minimum distributions
- Coordinating charitable giving with retirement income
Planning note:
Tax Planning is a year round activity and should not be delayed until Tax Season.
Strategic Considerations
A well-designed retirement plan should consider more than investment performance and income needs.
Taxes can influence how much money is available to spend, how retirement accounts are used, and how assets are ultimately transferred to beneficiaries.
While no strategy can eliminate taxes entirely, thoughtful planning may help retirees manage their tax liability and make more efficient use of their financial resources.
The objective is not simply to minimize taxes in any single year, but to develop a coordinated strategy that helps minimize taxes over a lifetime.
Key Takeaways
Retirement planning is not just about how much wealth you accumulate. It is also about how effectively you use that wealth throughout retirement.
Understanding how different income sources are taxed, planning ahead for future withdrawals, and regularly reviewing your financial situation can all play an important role in your long-term retirement plan.
At Palabe Wealth, we believe tax planning should be integrated into the broader retirement planning process. By evaluating how taxes interact with investments, retirement income, Social Security, and other financial decisions, we help clients make more informed choices about their financial future.
As always, Palabe Wealth is here to help. If you have any questions regarding your financial plan, please feel free to reach out at elliot.palabe@lpl.com.
References
- Internal Revenue Service, Distributions from Individual Retirement Arrangements (IRAs); Topic No. 409, Capital Gains and Losses.
- Internal Revenue Service, Roth IRAs; Required Minimum Distributions (RMDs); Rollovers of Retirement Plan and IRA Distributions.
- Social Security Administration, Income Taxes and Your Social Security Benefit.
- Medicare.gov, Medicare Costs at Higher Income Levels.
Disclosures
This material is for general informational purposes only and is not intended to provide specific tax, legal, or investment advice. Individuals should consult with their tax advisor, financial professional, or attorney regarding their unique circumstances.
Roth conversions are subject to income taxes on taxable amounts converted. Qualified Roth IRA distributions are generally tax-free, provided applicable requirements are satisfied. Investing involves risk, including possible loss of principal.
Securities and advisory services offered through LPL Financial, a registered investment advisor and member FINRA/SIPC. Palabe Wealth and LPL Financial are separate entities.
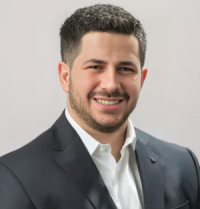
Elliot Palabe, CFP®
Elliot Palabe is a Wealth Advisor at Palabe Wealth, where he plays a pivotal role in designing comprehensive retirement plans and working directly with clients to address their financial needs. Elliot's expertise lies in his ability to combine personalized Financial Planning with strategic Tax Planning, helping to ensure that each client's financial strategy is both optimized and aligned with their individual goals and circumstances.
Elliot has a solid educational foundation that underpins his professional acumen, as he holds a Bachelor’s degree in Finance from the Foster College of Business at Bradley University. His academic background has provided him with a deep understanding of financial markets, investment strategies, and economic principles.
Elliot is a CERTIFIED FINANCIAL PLANNER™ professional. He holds several critical financial industry licenses, including the Series 65, 63, 6, and SIE, held through LPL Financial. These qualifications enable him to offer comprehensive investment guidance and demonstrate his thorough knowledge of the financial services industry.
A specialist in the use of sophisticated financial planning and tax planning software, Elliot brings a technological edge to his approach. This expertise allows him to create detailed and highly personalized financial plans that can adapt to changing market conditions and tax environments. By leveraging cutting-edge technology, Elliot ensures that Palabe Wealth's clients receive the most accurate, up-to-date, and effective financial advice possible.
His work is instrumental in helping clients navigate the complexities of financial planning and retirement preparation, helping to ensure they are well-positioned to pursue their long-term financial objectives.
Outside of work, Elliot competes in pickleball. The game’s blend of strategy and precision reflects the same qualities he brings to financial advising - thoughtful planning, attention to detail, and focus.